By Daniel Schulz, residir GmbH · Last updated: 14 October 2026
Under holiday rental tax rules in Germany, hosts pay income tax on the surplus of rental income minus deductible expenses (Werbungskosten), usually declared as income from letting and leasing (Vermietung und Verpachtung) on Annex V (Anlage V) of the tax return. In addition, VAT (Umsatzsteuer) of 7 per cent normally applies unless you qualify as a small business (Kleinunternehmer). Trade tax (Gewerbesteuer) is only payable if the letting is organised like a hotel business.
This guide explains tax on a holiday apartment from the host’s perspective, from depreciation and personal use through to selling. Our author Daniel Schulz has looked after more than 80,000 guest stays in eight years with serviced apartments and knows the questions owners ask about receipts and statements. The information is correct as of October 2026. This article is a general overview and not individual tax advice.
In this article:
- Which taxes apply
- Income tax: letting or business
- Deductible expenses and depreciation
- Personal use and hobby letting
- VAT and the small business rule
- Trade tax
- Platform reporting obligations
- Property tax and other levies
- Tax when selling
- Tips: receipts, calculators, tax advisers
- Conclusion
- FAQ
| Tax | When it applies | Legal basis |
|---|---|---|
| Income tax (Einkommensteuer) | Always on the surplus, as letting (Annex V) or business (Annex G) | Sections 15, 21 EStG |
| VAT (Umsatzsteuer) | Short-term letting at 7%, except for small businesses | Section 4 no. 12, Section 12(2) no. 11, Section 19 UStG |
| Trade tax (Gewerbesteuer) | Only for commercial, hotel-like letting; allowance of €24,500 | Section 11 GewStG |
| Property tax (Grundsteuer) | Annually for the owner, deductible as an expense | BayGrStG (Bavaria) |
| Tax on sale | Sale within ten years of purchase | Section 23 EStG |
Holiday rental tax in Germany: which taxes apply
Tax on a holiday apartment arises at several points. The most important is income tax, because it affects every host, however few nights they let per year. VAT depends on the level of turnover, and trade tax on the way you let the property.
If you want to let a holiday apartment privately, you pay tax under the same laws as a professional; there is no special tax-free allowance just for holiday apartments. For private letting, the tax position is determined mainly by how often you let, whether you use the flat yourself and what services you offer in addition to accommodation. How to set up the letting in principle, from the permit to pricing, is covered in our guide to renting out a holiday apartment.
Income tax: letting and leasing or a commercial business
If you let a holiday apartment privately, for tax purposes you will in most cases earn income from letting and leasing under Section 21 EStG (Einkommensteuergesetz, the German Income Tax Act). This also applies if you provide bed linen, charge a final cleaning fee or hand over the key via a key safe. Such services are part of a normal holiday apartment.
The letting only becomes commercial under Section 15 EStG when it resembles an accommodation business. In the Income Tax Guidance Notes (H 15.7(2) EStH), the tax authorities name two scenarios for this:
- Holiday complex with a holiday service: the fully furnished flat is in a complex with many similar flats in a holiday area, a holiday service organisation handles advertising and letting, and staff are permanently present, as at a hotel reception.
- Hotel-like use: the flat is run like a guesthouse; frequent changes of guests or additional services such as daily cleaning, breakfast or guest care require a business-like organisation.
Under these criteria, a single flat with final cleaning and a key safe generally remains private asset management. Only additional services on the scale of a hotel or several units with their own staff tip the balance towards a business.
Registering a business for a holiday apartment: when?
Under Section 14 GewO (Gewerbeordnung, the German Trade Regulation Act), you must register a business (Gewerbeanmeldung) for your holiday apartment as soon as the letting is commercial. The law does not set a fixed number of flats or overnight stays. Many trade offices (Gewerbeämter) mainly ask about additional services and organisation.
Registering a business does not in itself make you a trader for tax purposes; what matters is the actual activity. Conversely, anyone who lets in a hotel-like way is commercial, even without registering. If in doubt, clarify the classification in writing with the tax office (Finanzamt) or a tax adviser.
Annex V, Annex G and hardship relief
Rental income goes on Annex V (Anlage V), with a separate one for each flat. Business income belongs on Annex G (Anlage G); the profit is then usually determined by a cash-basis income statement (Einnahmen-Überschuss-Rechnung, Anlage EÜR).
For employees who let a holiday apartment on the side, hardship relief (Härteausgleich) under Section 46 EStG is important: secondary income of up to €410 a year remains tax-free, and up to €820 the tax is reduced. If secondary income exceeds €410, filing a tax return is mandatory.
Deductible expenses: offsetting holiday apartment costs against tax
What is taxed is not the rent but the surplus. You can deduct all costs arising from the letting as expenses (Werbungskosten):
- Depreciation on the building and furnishings
- Interest on the loan, but not the repayments
- Cleaning, laundry, consumables for guests
- Commissions and fees of booking platforms
- Electricity, heating, water, internet, broadcasting licence fee (Rundfunkbeitrag)
- Service charges (Hausgeld), insofar as they do not go into the maintenance reserve
- Property tax, insurance, repairs
- Tax advice, software, journeys to the flat
Cleaning costs for the holiday apartment reduce your tax in full if you let the flat exclusively. Conversely, if you charge guests a final cleaning fee, that amount is income. What belongs on a holiday rental invoice in practice, and which tax rate applies to each item, is explained in our guide with a sample.
Holiday apartment depreciation: the building
Depreciation (Absetzung für Abnutzung, AfA) is often the largest item. Only the building’s share of the purchase price plus incidental costs is depreciated, not the share for the land. Under Section 7(4) EStG, the following rates apply:
| Completion of the building | Depreciation per year | Useful life |
|---|---|---|
| Before 1925 | 2.5% | 40 years |
| 1925 to end of 2022 | 2% | 50 years |
| From 1 January 2023 | 3% | around 33 years |
Be careful with renovations immediately after purchase: if repair costs in the first three years exceed 15 per cent of the building costs (excluding VAT), they count as acquisition-related production costs (anschaffungsnahe Herstellungskosten) under Section 6(1) no. 1a EStG. They are then not deducted immediately, but spread over the building depreciation.
Depreciation of holiday apartment furnishings
Furniture, appliances and equipment are separate assets. The furnishings of a holiday apartment therefore count as deductible expenses, but according to fixed rules:
- Up to €800 net per item: deductible immediately in the year of purchase (low-value asset, geringwertiges Wirtschaftsgut).
- More expensive items: depreciated over their useful life according to the official depreciation table (AfA-Tabelle), for example a sofa or a large bed.
- Fitted kitchen: according to case law of the Federal Fiscal Court (Bundesfinanzhof, BFH, judgment of 3 August 2016, IX R 14/15), depreciated as a single unit over ten years.
To depreciate holiday apartment furnishings, you need the invoice for each individual item. If you bought the flat furnished, have the purchase price split in the contract between building, land and contents.
Apartments in Lehel from autumn 2027
From autumn 2027, residir GmbH will let a total of 54 apartments between 25 and 50 m² at Ländstraße 6, with their own kitchen, fast Wi-Fi, towels and bed linen, plus 24-hour safe check-in. Lehel U-Bahn station and Isartor S-Bahn station are just a few minutes’ walk away. Find out more on our page about serviced apartments in Munich.
Personal use and hobby letting: when the tax office asks questions
Many owners want to use their holiday apartment themselves and let it for the rest of the year. For tax purposes, personal use has two consequences: costs are split, and the tax office checks whether you intend to make a profit at all.
Letting exclusively: profit intention is assumed
If the holiday apartment is let exclusively to changing holiday guests and kept available for this purpose the rest of the time, the tax authorities assume an intention to generate income without further examination (Federal Ministry of Finance (BMF) letter of 8 October 2004, BStBl I 2004, 933). Vacant periods then count as letting, and costs are fully deductible.
There is still a limit, however: if letting falls more than 25 per cent below the usual local letting period, i.e. below 75 per cent of the usual occupancy days, the tax office requires a forecast (BFH, judgment of 26 October 2004, BStBl II 2005, 388). You can find out the usual local period from the local tourism association or statistics office, for example.
Tax with personal use of the holiday apartment: splitting costs
If you also use the holiday apartment yourself, only the share of costs attributable to letting is deductible for tax purposes. The basis is the ratio of letting days to days of personal use. If you reserved the right to use the flat yourself at any time, vacant days are also split in this ratio.
A worked example with sample figures: 120 days let, 30 days of personal use, the rest vacant. You can then deduct 120 out of 150 days, i.e. 80 per cent of the annual costs. If you contractually exclude personal use, for example through a letting agency, you can instead allocate vacant periods fully to the letting.
When the holiday apartment counts as a hobby and losses are disallowed
If you use the flat yourself or reserve the right to do so, the tax office requires a total surplus forecast (Totalüberschussprognose) over 30 years. The BFH has confirmed this even for cases in which usual local letting periods cannot be determined (judgment of 19 August 2008, IX R 39/07). If the forecast shows no surplus, the letting is treated as a hobby (Liebhaberei): losses are not recognised, but any later profits then also remain tax-free.
The forecast takes into account income and costs over the full 30 years; loans with a heavy interest burden in the early years weigh heavily. If you want to claim losses, you should be able to document your letting efforts: listings, enquiries, price adjustments.
VAT on holiday apartments: 7 per cent and the small business rule
Long-term letting of residential space is exempt from VAT. Under Section 4 no. 12 sentence 2 UStG (Umsatzsteuergesetz, the German VAT Act), this exemption does not apply to the short-term accommodation of guests. VAT is therefore charged on holiday apartments, at the reduced rate of 7 per cent (Section 12(2) no. 11 UStG).
If you want to let a holiday apartment, you only have to pay VAT if you do not fall under the small business rule (Kleinunternehmerregelung). Since 2025, Section 19 UStG applies: no more than €25,000 turnover in the previous year and no more than €100,000 in the current year. All business turnover is counted together, not just that of the holiday apartment.
Small businesses save themselves advance VAT returns, but may not deduct input VAT from invoices for furnishings or renovation. If you opt out of the rule, you are bound by that choice for five calendar years. With high initial investment, opting out can pay off, but a tax adviser should run the numbers.
Services that do not directly serve the accommodation, such as a parking space or drinks, are subject to 19 per cent and shown separately. An invoice with VAT shown is particularly important for business customers, for example if you let your flat as workers’ accommodation in Munich to trade businesses.
Tax if you let the holiday apartment long-term
If you let the holiday apartment long-term, i.e. to one tenant for many months as a home, you are in the territory of normal residential letting for tax purposes. VAT no longer applies, and the income remains letting and leasing on Annex V. Obligations that apply to short-stay guests, such as showing items separately by tax rate, fall away.
Whether a contract lasting several months counts as short-term accommodation or as a residential tenancy depends on the intention when the contract is concluded. Tenancy law questions on the term are explained in our guide to the fixed-term lease in Germany. If you let a furnished flat for longer, record the inventory and furnishing surcharge in the contract.
Trade tax: only for commercial letting
Only those who let commercially pay trade tax (Gewerbesteuer). For sole traders and partnerships, there is an allowance of €24,500 trade income per year (Section 11(1) GewStG). Above that, the municipality sets the tax using its local multiplier (Hebesatz).
For sole traders, trade tax is partly credited against income tax under Section 35 EStG. Another consequence is often more important: with commercial letting, the flat forms part of business assets (Betriebsvermögen). A later sale is then always taxable, even after more than ten years.
Platforms report income to the tax office
Since 2023, the Platform Tax Transparency Act (Plattformen-Steuertransparenzgesetz, PStTG), with which Germany implemented the EU directive DAC7, has been in force. Booking platforms report their hosts’ data to the Federal Central Tax Office (Bundeszentralamt für Steuern) by 31 January of the following year. From there it is passed on to the relevant tax offices, and hosts are informed about the data reported.
For property, the data reported include the address of each flat, the payments made, the number of bookings and, where known, the number of days let. The de minimis threshold of 30 sales and €2,000 applies only to the sale of goods; there is no such threshold for letting a single holiday apartment. If letting income was not declared in previous years, you should clarify this promptly with a tax adviser.
If you declare your income in full anyway, you will notice little of the reporting. However, do compare your figures with the platform’s annual summary, because the tax office sees the same values. Especially in months with many bookings, for example when guests are looking for accommodation near Messe Munich, the amounts add up quickly.
Property tax and other levies
Property tax (Grundsteuer) is paid by the owner, regardless of whether the property is let. In Bavaria, since 2025 it has been calculated using the area-based model of the Bavarian Property Tax Act (Bayerisches Grundsteuergesetz). When letting, it is a deductible expense; with personal use, proportionately.
In addition, some municipalities charge their own levies, such as a spa tax (Kurbeitrag), tourism levy (Fremdenverkehrsbeitrag) or second home tax (Zweitwohnungsteuer), and many cities regulate short-term letting through permits. Clarify these questions directly with your municipality. Guests searching for holiday apartments in Munich notice none of this, but for hosts the local rules need to be sorted before the first listing.
Tax when selling a holiday apartment
If you sell a holiday apartment held as private assets within ten years of purchase, the gain is taxable as a private sale transaction (privates Veräußerungsgeschäft) under Section 23 EStG. The dates of the notarised purchase contracts are decisive. The gain remains tax-free up to a total gain from such transactions of €1,000 per year (exemption limit since 2024).
The well-known exemption for owner-occupied property only applies if you used the flat for your own residential purposes in the year of sale and the two preceding years, or continuously since purchase. The BFH has ruled that a holiday apartment can also qualify, but only if it is not intended for letting (judgment of 27 June 2017, IX R 37/16). A let holiday apartment can therefore only be sold tax-free after ten years.
- Depreciation increases the gain: depreciation claimed reduces the acquisition costs and thus increases the taxable capital gain.
- Commercial letting: if the flat forms part of business assets, the gain is taxable with no time limit.
- Multiple sales: anyone who buys and sells more than three properties within five years may be treated as a commercial property dealer (the tax authorities’ three-property rule, Drei-Objekt-Grenze).
Tax calculators, WISO and tax advisers: tips for your return
The tax burden can only be calculated with your personal tax rate, because income from the holiday apartment is added to your other income. An online holiday rental tax calculator therefore only provides a rough estimate. For your own rough calculation, this outline is sufficient:
| Step | What goes in |
|---|---|
| Income | All payments from guests incl. final cleaning, excluding VAT collected under standard taxation |
| minus deductible expenses | Depreciation, interest, cleaning, commissions, running costs, property tax, insurance |
| = surplus or loss | Added to your other income |
| × personal tax rate | Gives the additional income tax, plus solidarity surcharge and church tax where applicable |
Tax software guides you step by step through Annex V. If you declare your holiday apartment with WISO Steuer, it is best to have the number of letting, personal use and vacant days to hand. With personal use, small business questions or commercial letting, a tax adviser is still worthwhile, and their fees are in turn deductible expenses.
You will only see what a holiday apartment actually costs you in tax and expenses after a full year of letting. Practical tips for your receipts:
- Keep a separate bank account just for the holiday apartment.
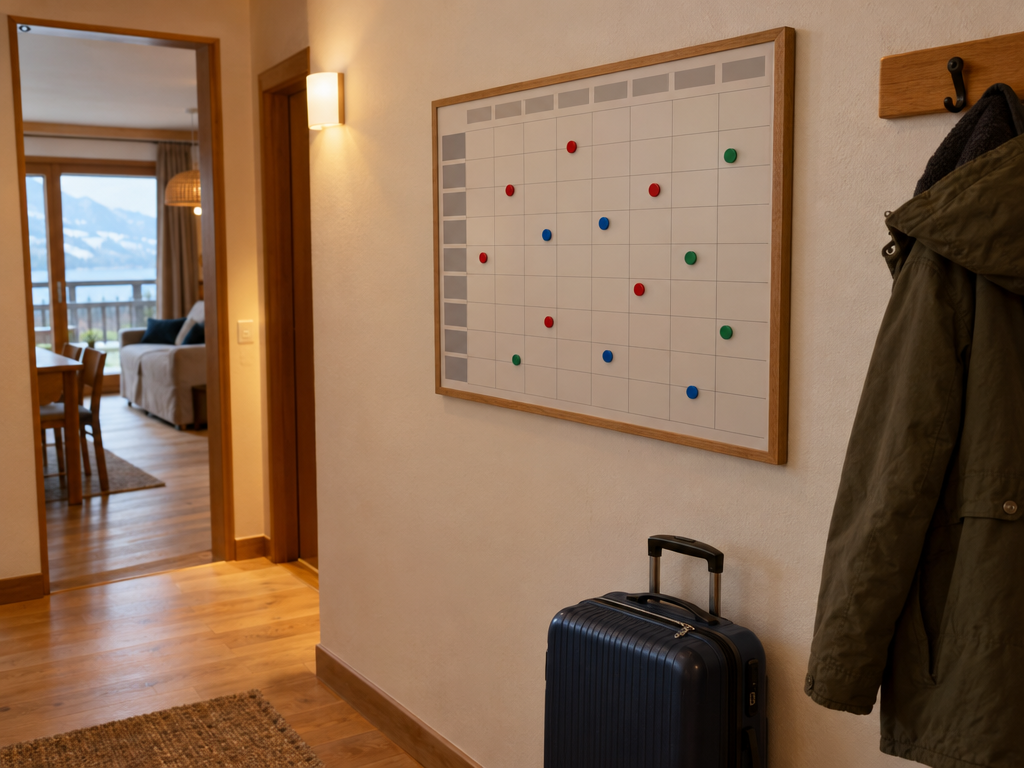
- Keep an occupancy calendar showing letting, personal use and vacant days.
- File invoices for furnishings individually, with date and net amount.
- Download the platforms’ monthly statements before they disappear from your account.
- Document listings and price changes in case the tax office asks about your intention to let.
From Daniel Schulz’s experience: most queries do not arise with the large items, but with small things such as undated cleaning invoices or platform payouts that bundle several bookings. If you allocate each payout to the individual stays, you save yourself this work.
If you let a flat not to holiday guests but to working professionals over a longer period, your accounts are simpler, because there are fewer bookings and payouts.
Conclusion
With a holiday apartment, hosts pay income tax on the surplus, usually as letting and leasing, plus 7 per cent VAT unless they are a small business, and trade tax only for hotel-like operations; if you document depreciation, expenses and personal-use days carefully, reconcile the platforms’ reports and keep an eye on the ten-year period when selling, you avoid the most common mistakes, and if you want less effort with guest changeovers, consider the model of furnished apartments in Munich.
Frequently asked questions about holiday rental tax in Germany
Do I have to pay tax on income from a holiday apartment?
Yes. Income from letting a holiday apartment is subject to income tax, usually as income from letting and leasing under Section 21 EStG, or as business income if the offer is hotel-like. What is taxed is the surplus of income over deductible expenses. As of October 2026.
Which holiday apartment costs can I deduct from tax?
All costs connected with the letting are deductible: depreciation on the building and furnishings, loan interest, cleaning and laundry, platform commissions, running costs, property tax, insurance, repairs and tax advice. With personal use, only the share attributable to letting counts.
How much depreciation can I claim on a holiday apartment?
The building’s share is depreciated on a straight-line basis under Section 7(4) EStG: 2 per cent per year for buildings completed between 1925 and the end of 2022, 2.5 per cent for older buildings and 3 per cent for buildings completed from 2023. The share for the land is not depreciated.
Do I have to pay VAT on my holiday apartment?
Short-term letting of a holiday apartment is subject to VAT at a rate of 7 per cent. If, as a small business under Section 19 UStG, your turnover was no more than €25,000 in the previous year and is no more than €100,000 in the current year, you do not charge VAT.
When do I have to register a business for my holiday apartment?
There is no fixed threshold. According to the tax authorities, letting becomes commercial when it is organised like a hotel, for example with permanently present staff, daily cleaning or breakfast, or when a holiday complex with a holiday service organisation handles the letting. Business registration and trade tax then become relevant.
What are the tax consequences if I use the holiday apartment myself?
With occasional personal use, only the costs attributable to the letting days are deductible. In addition, the tax office then requires a 30-year forecast of whether an overall surplus will arise. If it is negative, the letting is treated as a hobby (Liebhaberei) and losses are not recognised.
Do booking platforms report my income to the tax office?
Yes. Under the Platform Tax Transparency Act, since the 2023 reporting period platforms have reported hosts’ payments by 31 January of the following year to the Federal Central Tax Office, which passes the data on to the tax offices. Hosts are informed about the data reported.
Do I have to pay tax when I sell my holiday apartment?
If less than ten years pass between purchase and sale, the gain is taxable as a private sale transaction under Section 23 EStG. The exemption for own residential use does not apply to a let holiday apartment. If the flat belongs to a commercial business, the gain is taxable regardless of the holding period.
Daniel Schulz · Managing Director of residir GmbH
He has eight years of experience in letting and managing serviced apartments and has looked after more than 80,000 guest stays. More about Daniel Schulz